How to Open an IRA: A Step-by-Step Guide
TL;DR: Opening an IRA breaks down into four steps: choose between a Traditional and a Roth IRA, choose a custodian or brokerage to hold the account, provide your information and fund it, and choose your investments. For the 2026 tax year, the combined Traditional-and-Roth contribution limit is $7,500, or $8,600 if you are age 50 or older, and the deadline to fund an account for 2026 is generally April 15, 2027.
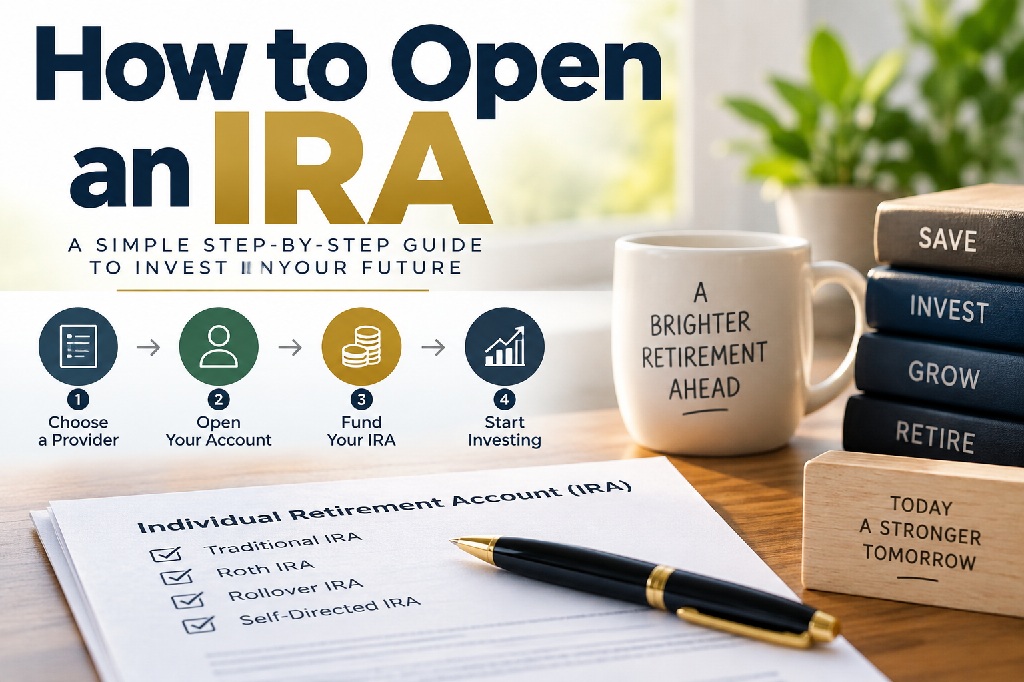
Step 1: Choose Traditional or Roth Before You Open Anything
The account type you pick determines how your contributions and withdrawals are taxed, and it is the one decision this whole process depends on.
Before walking through the mechanics below, see our broader guide to IRA investing for how a Traditional or Roth IRA fits into a full retirement plan, and our types of IRA accounts breakdown if you are still comparing account categories generally. This guide assumes you already know you want a Traditional or Roth IRA and just need the setup steps.
The core difference is timing of the tax bill. A Traditional IRA contribution may be tax-deductible in the year you make it, subject to income and workplace-coverage limits, and withdrawals in retirement are generally included in taxable income except for the portion that represents your own already-taxed contributions. A Roth IRA works the opposite way. The Internal Revenue Service states plainly on its Roth IRA page that “you cannot deduct contributions to a Roth IRA,” but qualified withdrawals in retirement come out completely tax-free under IRC section 408A(d)(1)(A) of the Internal Revenue Code. For the full mechanics and eligibility rules of each account type, see our Traditional IRA guide and Roth IRA guide. Once you know which type you want, or whether you want both, the remaining steps are the same.
Step 2: Choose a Custodian or Brokerage
Every IRA custodian offers the identical tax wrapper, so the real decision comes down to fees, investment menu, and account features, not the brand name on the account.
An IRA is not itself an investment. It is a legal account structure that a custodian, typically a brokerage, bank, or trust company, holds on your behalf and reports to the IRS each year. When comparing providers, look at what each one actually offers: the breadth of the investment menu, account fees and any minimum balance requirement, and whether customer support and account tools fit how you plan to manage the account. This guide stays educational and does not recommend a specific brokerage.
If your goal includes holding assets a standard brokerage IRA does not offer, such as real estate or other alternative assets, you will need a custodian that supports a self-directed IRA structure. Our self-directed IRA guide explains how that structure differs from a conventional brokerage account and what it takes to open one. For most savers who plan to hold stocks, bonds, mutual funds, or exchange-traded funds, a standard brokerage IRA is sufficient and the account-opening process below applies either way.
Step 3: Provide Your Information and Fund the Account
You can open an IRA at any point in the year, but how much you can put into it is capped by your taxable compensation and by an annual dollar limit that increased for 2026.
Opening the account itself is a paperwork step: you provide identifying information, designate a beneficiary, and choose how you want to fund it, typically by bank transfer, a check, or a rollover from another retirement account. The part that requires attention is how much you are allowed to contribute.
The Internal Revenue Service confirmed in News Release IR-2025-111 that the annual IRA contribution limit for 2026 rises to $7,500, combined across your Traditional and Roth IRAs together rather than per account. Savers age 50 and older get an additional catch-up contribution, which increases to $1,100 for 2026, bringing the total to $8,600. Contributions are also capped at your taxable compensation for the year if that figure is lower than the dollar limit. The IRS states the rule directly on its retirement-topics contribution-limits page: the total contributed “cannot be more than $7,500 ($8,600 if you’re age 50 or older), or if less, your taxable compensation for the year.”
If you do not have taxable compensation of your own, you may still be able to fund an IRA. Under the spousal IRA provision at IRC section 219(c) of the Internal Revenue Code, a married couple filing a joint return can contribute on behalf of a spouse with no compensation, based on the working spouse’s income, subject to the same combined dollar limit.
Timing matters too. IRS Publication 590-A sets the funding deadline as the return due date for the year, not including extensions, generally April 15 of the following year. Applying that rule to the 2026 tax year, a contribution for 2026 is generally due by April 15, 2027. If you contribute between January 1 and that April deadline, tell your custodian which tax year the contribution is for, since a contribution made in that window can count toward either the prior year or the current one.
Watch the limit closely. Contribute more than the allowed amount and the excess is subject to a 6 percent excise tax under IRC section 4973(a), assessed for every year the excess remains in the account. You can avoid the tax by withdrawing the excess contribution plus any attributable earnings before your filing deadline, or by applying the excess toward a later year’s limit. Excess contributions and the related tax are reported on Form 5329.
Step 4: Choose Your Investments
An open, funded IRA is still an empty shell until you select investments inside it, and that choice is what actually drives your long-term return, not the account type itself.
Once the account is funded, the custodian will not automatically invest the cash. You choose the holdings, which in a standard brokerage IRA typically means selecting from stocks, bonds, mutual funds, and exchange-traded funds, and in a self-directed IRA can extend to a wider range of IRS-eligible alternative assets. For a full walkthrough of what can go inside an IRA and how to think about allocating it, see our IRA investment options guide. Leaving new contributions sitting in cash inside the account is a common early mistake worth avoiding once you have completed the first three steps.
What Happens If You Contribute Too Much
Going over the annual limit is a fixable mistake, not a permanent one, as long as you correct it before it compounds year over year.
As noted in Step 3, the 6 percent excise tax under IRC section 4973(a) applies annually to any excess left in the account, calculated on the value of the account at year-end. The fix is straightforward. Withdraw the excess contribution and any earnings it generated before your tax filing deadline, including extensions, to avoid the tax for that year, or absorb the excess against a future year’s contribution limit if you are under that year’s cap. Either correction is documented on Form 5329, which the IRS uses to track and assess excess-contribution penalties.
Frequently Asked Questions
Do I need a job to open an IRA?
You need taxable compensation to contribute to an IRA in your own name, but the spousal IRA provision under IRC section 219(c) lets a non-earning spouse contribute based on a working spouse’s income when filing jointly. Opening the account itself has no employment requirement beyond that funding rule.
How much can I contribute to an IRA in 2026?
The combined limit across your Traditional and Roth IRAs is $7,500 for 2026, or $8,600 if you are age 50 or older, and you cannot contribute more than your taxable compensation for the year if that amount is lower.
What is the deadline to fund an IRA for the 2026 tax year?
You can open an IRA at any time, but a contribution counted toward the 2026 tax year is generally due by the return filing deadline, not including extensions, which is April 15, 2027.
Can I have both a Traditional and a Roth IRA at the same time?
Yes. You can hold and contribute to both in the same year, but the $7,500 or $8,600 limit applies to your combined contributions across both accounts, not to each one separately.
Is a Roth IRA contribution tax deductible?
No. The IRS states directly that Roth IRA contributions cannot be deducted, unlike Traditional IRA contributions, which may be deductible depending on income and workplace-plan coverage.
What happens if I contribute more than the annual limit?
The excess is subject to a 6 percent excise tax for every year it stays in the account under IRC section 4973(a). You can avoid or stop the tax by withdrawing the excess and its earnings by your filing deadline, or by applying it to a later year’s contribution limit, reported on Form 5329.
Always consult your own legal, financial, and tax professionals before opening or changing a retirement account.
By Tim Schmidt + Sean Webster Reviewed by Sean Webster