IRA Investment Options: What Can an IRA Actually Hold?
TL;DR: An IRA can hold most publicly traded securities (stocks, bonds, mutual funds, ETFs) through a standard brokerage custodian and bank CDs through a bank custodian, and a much wider menu of alternatives, including real estate, private placements, promissory notes, precious metals, and crypto, through a self-directed IRA custodian. Federal law bars only two categories outright: life insurance contracts and most collectibles, plus a separate rule that keeps an IRA from owning S-corporation stock. The self-directed custodian that opens the door to alternatives does not vet, evaluate, or verify any of them, so the due-diligence burden sits entirely with the account owner. This is educational information, not individualized investment, legal, or tax advice.
What Can an IRA Invest In?
An IRA’s investment menu splits into three tiers: what a standard custodian offers, what a self-directed custodian adds, and a short list the law rules out entirely.
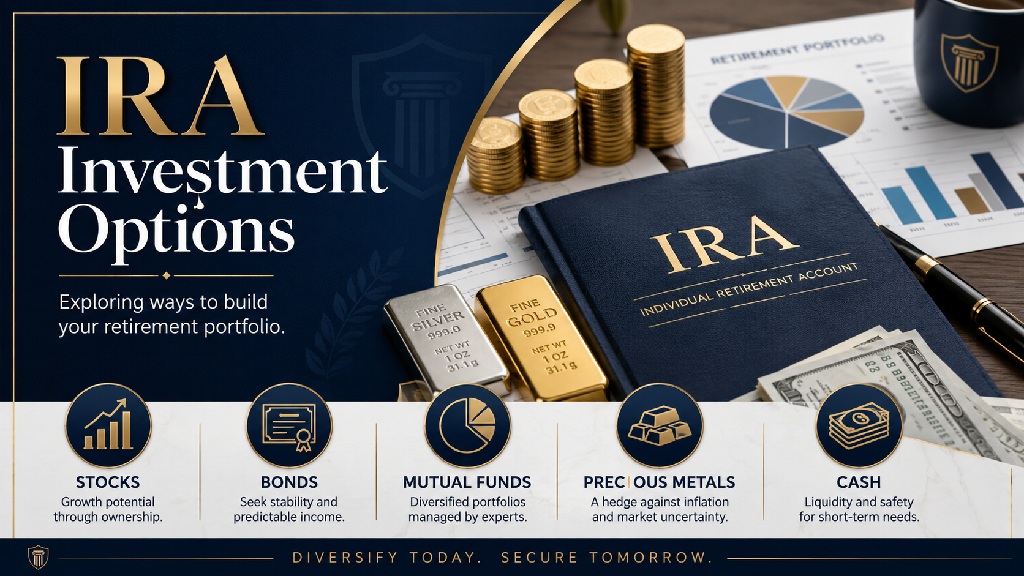
A standard, or “brokerage,” IRA custodian typically limits holdings to firm-approved stocks, bonds, mutual funds, ETFs, and CDs. A self-directed IRA, a version of the same account held by a custodian willing to administer alternative assets, opens the door to real estate, private notes, private equity, tax liens, precious metals, and crypto. The Securities and Exchange Commission confirms this split directly, noting that “most custodians for other types of IRAs limit the holdings in IRA accounts to firm-approved stocks, bonds, mutual funds, and CDs,” while self-directed custodians “may allow investors to invest retirement funds in ‘alternative assets’ such as real estate, precious metals and other commodities, crypto assets, private placement securities, promissory notes, and tax lien certificates.” A short list sits outside both tiers because federal statute prohibits it, covered below. The IRA wrapper itself does not pick the menu. The custodian does.
What a Standard Brokerage or Bank IRA Can Hold
A standard IRA at a brokerage or bank covers the assets most retirement savers already recognize: public securities and insured deposits.
Stocks, bonds, mutual funds, and exchange-traded funds trade through a brokerage IRA and make up the bulk of mainstream retirement holdings. A bank IRA can instead hold a certificate of deposit, a fixed-term, fixed-rate deposit product. IRA deposits, including CDs, are FDIC-insured under the “Certain Retirement Accounts” ownership category, and the Federal Deposit Insurance Corporation states it “adds together all certain retirement accounts owned by the same person at the same [bank] and insures the total up to $250,000.” That protection covers deposit products only. Stocks, bonds, mutual funds, and other securities held in a brokerage IRA are not FDIC-insured, since FDIC coverage extends to CDs and similar deposits, not to investments. Nothing about this tier requires a self-directed custodian. It is the default menu most IRA providers already offer.
What a Self-Directed IRA Adds to the Menu
A self-directed IRA does not change the tax wrapper. It changes who is willing to hold the asset, opening the account to real estate, private notes, private equity, tax liens, precious metals, and crypto.
The same SEC alert that describes the standard-account limits lists the alternative side of the ledger: real estate, precious metals and other commodities, crypto assets, private placement securities, promissory notes, and tax lien certificates. Every IRA custodian, standard or self-directed, must itself be approved. The SEC notes that “all IRA accounts are held for investors by custodians, which may include banks, trust companies, or any other entity approved by the Internal Revenue Service” as a nonbank trustee. That approval covers the custodian’s fitness to administer the account, not whether any specific asset inside it is sound, a distinction covered in full further down this page.
What an IRA Can Never Hold
Federal law prohibits only two categories of IRA investment outright, plus a separate rule against S-corporation ownership, and no custodian, self-directed or otherwise, can override any of the three.
The statute that creates IRAs states plainly, under IRC section 408(a)(3): “No part of the trust funds will be invested in life insurance contracts.” The second prohibition covers collectibles. Under IRC section 408(m)(2), a “collectible” is defined as any work of art, rug or antique, metal or gem, stamp or coin, alcoholic beverage, or other tangible personal property the Treasury Secretary specifies for this purpose, and buying one inside an IRA is treated as an immediate taxable distribution equal to its cost. Section 408(m)(3) then carves out a narrow exception for specific gold, silver, platinum, and palladium coins and bullion meeting minimum fineness standards, provided the metal sits in the physical possession of a trustee rather than the account owner. The Tax Court confirmed that boundary in McNulty v. Commissioner, 157 T.C. No. 10 (2021), ruling that an account owner who kept roughly $411,000 in American Eagle coins in a home safe had taken an unfettered, taxable distribution. Separately, an IRA cannot be an S-corporation shareholder. The IRS ruled in Revenue Ruling 92-73 that “a trust that qualifies as an individual retirement account under section 408(a) of the Code is not a permitted shareholder of an S corporation under section 1361,” a position the Ninth Circuit affirmed in Taproot Administrative Services, Inc. v. Commissioner, 679 F.3d 1109 (2012).
Real Estate Inside an IRA: The Rules That Trip People Up
Real estate is permitted inside a self-directed IRA, but two rule sets, the prohibited-transaction rules and the debt-financing tax, catch more owners than the purchase itself ever does.
Real estate held in an IRA is subject to the prohibited-transaction rules under IRC section 4975. The IRS describes a prohibited transaction as “any improper use of an IRA account or annuity by the IRA owner, his or her beneficiary or any disqualified person,” and disqualified persons include the owner’s fiduciary and close family members, such as a spouse, ancestor, or lineal descendant. In practice, that framework is why the owner and other disqualified persons generally cannot personally use IRA-owned property or perform labor on it, and why every expense and every dollar of rental income must flow through the IRA. A second trap sits in the financing. If the property carries a mortgage, the debt-financed portion of the income can trigger unrelated business income tax. IRS Publication 598 lists IRAs among the trusts subject to this tax, and IRC section 514 pulls debt-financed income into the taxable base in proportion to the acquisition debt. Unlike a qualified employer retirement plan, an IRA does not qualify for the real-property financing exception under section 514(c)(9), so a leveraged IRA-owned property commonly does owe this tax on its debt-financed share of income. Once gross unrelated business income reaches $1,000 in a year, the IRA must file its own Form 990-T.
Crypto in an IRA: Permitted, Not Approved
Crypto is not on the collectibles list and is not life insurance, so no statute bars an IRA from holding it, but that is a gap in the prohibition, not an IRS endorsement.
The IRS treats virtual currency as property for federal tax purposes, a position it set in Notice 2014-21 and retained through Notice 2023-34. Because crypto does not appear in section 408(m)(2)’s collectibles list and is not a life insurance contract under section 408(a)(3), nothing in the statute stops an IRA from holding it. That is an inference from what the statute does not say, not an affirmative ruling that crypto is a permitted or approved IRA asset. The Commodity Futures Trading Commission has warned directly against sales pitches that describe crypto IRAs as “IRS approved,” stating that agencies including the CFTC and IRS do not “endorse any investment” or “advise people on how to invest their money,” and that holding crypto inside an IRA does nothing to reduce its price volatility. The CFTC also flags custody risk specific to crypto: digital wallets can be hacked, and stolen or lost digital assets may be unrecoverable. Crypto inside an IRA is held through a self-directed custodian arrangement, with the custodian or a third party holding the assets rather than the owner holding the keys directly.
IRA CDs: FDIC-Insured, But Two Separate Penalties Can Apply
An IRA CD is FDIC-insured up to $250,000, but breaking it early can trigger two distinct penalties that are easy to conflate.
A CD held inside an IRA locks in a fixed rate for a set term at an FDIC-insured bank acting as custodian. Federal rules set a minimum early-withdrawal penalty, and individual banks typically set their own schedule above that floor under Regulation DD. That is a contractual, bank-level penalty for breaking the CD before maturity, and it is entirely separate from the IRS’s rule on IRA distributions. If funds actually leave the IRA before age 59 and a half, the IRS states that “you’ll be assessed a 10% additional tax on early distributions from traditional and Roth IRAs, unless an exception applies,” under IRC section 72(t). Cashing a matured or broken CD and rolling the proceeds into another IRA within the rollover rules avoids that 10% tax entirely, since no distribution out of the IRA wrapper has occurred. An account holder can owe the bank penalty, the IRS tax, both, or neither, depending on what actually happens to the money.
Precious Metals: A Narrow Statutory Exception, Not a Free-For-All
Gold, silver, platinum, and palladium can sit inside an IRA only under the specific coin and bullion exception in the collectibles rule, and only when the metal is held by a trustee rather than the owner.
Section 408(m)(3)’s coin and bullion exception is narrow by design: it covers specific gold, silver, and platinum coins plus any coin issued under state law, along with gold, silver, platinum, or palladium bullion meeting a minimum fineness standard, and it requires the metal to remain in the physical possession of a trustee. Metals purchased outside that exception, or stored at home, fall back under the general collectibles rule and are treated as a taxable distribution. This page stays with the general investment menu. For the mechanics of moving retirement funds into metals and choosing a self-directed structure built for that purpose, see this hub’s dedicated coverage of the self-directed IRA and the gold IRA rollover process.
Who Actually Vets These Alternative Investments?
Nobody vets them on the account owner’s behalf, and that is the single most misunderstood part of self-directed investing.
The SEC states plainly that self-directed IRA custodians “DO NOT sell investment products or provide investment advice,” “DO NOT evaluate the quality or legitimacy of any investment in the self-directed IRA or its promoters,” and “DO NOT verify the accuracy of any financial information that is provided for an investment in the account.” NASAA’s investor advisory makes the same point from the regulator side, stating that a third-party custodian “does NOT research or perform due diligence reviews or recommend investments to clients” and functions as “a passive company that simply serves as an intermediary between the investor and the issuer of an investment.” Being IRS-approved as a custodian is a separate fact from any investment inside the account being sound. With a self-directed IRA, the SEC notes, “you have sole responsibility for evaluating and understanding the investments in the account.” The SEC also warns that fraud is a real risk in this category precisely because “using a legitimate custodian to buy an investment DOES NOT make that investment legitimate.”
Does It Matter If the Account Is a Traditional or a Roth IRA?
The investment menu itself does not change between a traditional and a Roth IRA. What changes is the tax treatment of contributions and withdrawals, not what the account is allowed to hold.
The prohibitions on life insurance, most collectibles, and S-corporation stock, along with the coin and bullion exception, apply to individual retirement accounts generally, so the same boundaries govern a Roth account as a traditional one. What differs between the two is covered on this hub’s dedicated breakdown of IRA account types and the Roth IRA page. For the full IRA investing library, this hub’s homepage is the starting point.
Frequently Asked Questions
What can an IRA invest in? A standard IRA can hold publicly traded stocks, bonds, mutual funds, ETFs, and CDs. A self-directed IRA can additionally hold real estate, private placements, promissory notes, precious metals within the section 408(m)(3) exception, and crypto.
What can you hold in an IRA? Anything except life insurance contracts, most collectibles as defined in IRC section 408(m)(2), and S-corporation stock. Everything else runs through either a standard custodian’s approved list or a self-directed custodian’s broader menu.
What can a Roth IRA invest in? The same menu as a traditional IRA. The investment rules under section 408 apply to individual retirement accounts generally, so account type changes the tax treatment, not the list of permitted investments.
Can you hold crypto in an IRA? Yes, through a self-directed custodian, because crypto is not listed as a prohibited collectible or as life insurance. That is a gap in the statute’s prohibitions, not an IRS endorsement or approval of crypto as an investment.
What can’t an IRA hold? Life insurance contracts under IRC section 408(a)(3), most collectibles under section 408(m)(2), and S-corporation stock under IRC section 1361. Precious metals are collectibles by default, with a narrow trustee-held exception under section 408(m)(3).
This page is educational information, not individualized legal, tax, or investment advice. Always consult your own legal, financial, and tax professionals before opening or changing a retirement account.
By Tim Schmidt + Sean Webster Reviewed by Sean Webster