Backdoor Roth IRA: How It Works (and the Pro-Rata Trap)
TL;DR: A backdoor Roth IRA is a two-step strategy, not a special account: make a nondeductible contribution to a Traditional IRA, then convert that money to a Roth IRA. It works regardless of income because the Internal Revenue Service caps income only on direct Roth contributions, never on conversions. The real danger is the pro-rata rule, which aggregates every Traditional, SEP, and SIMPLE IRA you own and can make part of a supposedly tax-free conversion taxable. Both steps get reported on Form 8606, and once you convert, the decision is permanent under current law. A related but separate strategy, the mega backdoor Roth, lets some 401(k) participants push after-tax contributions into a Roth up to the combined $72,000 IRC section 415(c) limit for 2026, if their plan allows it.
What a Backdoor Roth IRA Actually Is
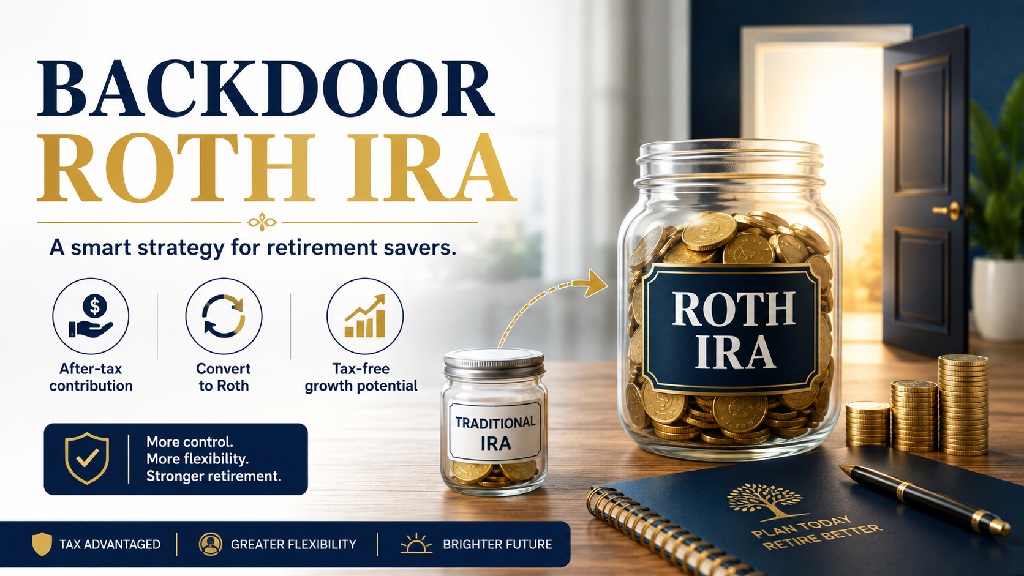
A backdoor Roth IRA is a nondeductible Traditional IRA contribution immediately converted to a Roth IRA, a two-step workaround built around a real gap in federal tax law.
For 2026, direct Roth IRA contributions phase out for single filers and heads of household with modified adjusted gross income between $153,000 and $168,000, and for married couples filing jointly between $242,000 and $252,000. Above those ranges, a saver cannot contribute to a Roth IRA directly. That income limit, however, applies only to direct contributions under IRC section 408A(c)(3). Conversions from a Traditional IRA to a Roth IRA are governed by a separate provision, IRC section 408A(d)(3), and that provision carries no income ceiling at all. The backdoor Roth simply uses the conversion path instead of the contribution path, and both are equally legal under the same statute. Traditional IRA contributions themselves are never income-limited either, only the tax deduction for them is, so any saver with enough taxable compensation can make the initial contribution regardless of income.
A backdoor Roth is one strategy within a much wider set of account options. For the fuller picture, see our overview of the different types of IRA accounts and our dedicated Roth IRA guide, or start from the IRA investing hub for the full landscape.
The Step-by-Step Mechanics
The process runs in a fixed sequence: make a nondeductible contribution to a Traditional IRA, report it, convert the balance to a Roth IRA, and report the conversion.
- Contribute to a Traditional IRA. The 2026 limit is $7,500, or $8,600 if you are 50 or older, the same cap that applies to any IRA contribution. Contributions for a given tax year are generally due by the return filing deadline, not including extensions, which falls around April 15 of the following year.
- Report the contribution as nondeductible on Form 8606 for that tax year. This is what creates your basis, the already-taxed portion of the account that should never be taxed again.
- Convert the Traditional IRA balance to a Roth IRA. Because conversions fall under IRC section 408A(d)(3) rather than the income-limited contribution rule, there is no MAGI ceiling on this step.
- Report the conversion on Form 8606 for the conversion year. This is also the step where the pro-rata rule determines how much of the conversion is taxable.
- Pay ordinary income tax on any portion of the converted amount that represents pre-tax money, based on the pro-rata calculation below.
Doing the contribution and the conversion close together, before the money has time to earn meaningful investment growth, limits how much of the conversion is attributable to earnings that would otherwise be taxable.
The Pro-Rata Rule: The Actual Trap
The pro-rata rule under IRC section 408(d)(2) aggregates every Traditional, SEP, and SIMPLE IRA you own into one pool for tax purposes, so if any of them holds pre-tax money, part of every conversion is taxable no matter which specific account the converted dollars came from.
The statute treats all individual retirement plans as one contract and all distributions in a year as one distribution. In practice, this means you cannot choose to convert your new nondeductible contribution first and leave older pre-tax money behind. Basis, the nondeductible portion you already paid tax on, is recovered proportionally across the entire pool, not withdrawn first. A saver whose only IRA is the new nondeductible contribution can convert it with little or no tax owed. A saver who also holds a pre-tax Traditional IRA, often from an old 401(k) rollover, will find that a meaningful share of every conversion is taxable, in proportion to how much of the combined pool is pre-tax.
Two exclusions matter here. Roth IRAs are carved out of this aggregation entirely, since IRC section 408A(d)(4)(A) applies the pro-rata rule separately to Roth IRAs and other individual retirement plans. Employer plan balances, such as a 401(k) or 403(b), are also excluded from the pool. That means pre-tax money sitting inside a workplace plan rather than an IRA does not trigger the pro-rata rule on a backdoor Roth conversion.
Form 8606: The Paperwork That Makes It Work
Form 8606 is the only record the IRS keeps of your nondeductible basis, and skipping it is the single most common way a backdoor Roth strategy goes wrong.
The form tracks nondeductible contributions and, in the conversion year, computes the taxable portion of a Roth conversion using the year-end value of all your Traditional, SEP, and SIMPLE IRAs combined. File it for the contribution year to establish basis, and again for the conversion year to calculate what portion of the conversion is taxable under the pro-rata rule. Because the taxable portion depends entirely on documented basis, disciplined contribution tracking across every IRA you own matters as much as the conversion itself. Without it, there is no documented basis, and the IRS has no way to distinguish already-taxed contributions from pre-tax money, which risks the entire converted amount being treated as taxable.
Why the Conversion Cannot Be Undone
Once the conversion happens, it is final: the Tax Cuts and Jobs Act eliminated conversion recharacterization for any conversion made on or after January 1, 2018, so a backdoor Roth cannot be reversed once completed.
Before 2018, a saver who converted to a Roth and later regretted it, often because of an unexpected tax bill, could recharacterize the conversion back to a Traditional IRA. That option no longer exists. Per IRS guidance, a conversion from a Traditional, SEP, or SIMPLE IRA to a Roth IRA cannot be recharacterized, a rule with its statutory basis in IRC section 408A(d)(6). This is a different rule from contribution recharacterization, which is still permitted. A saver can still redesignate a current-year regular contribution between a Traditional and a Roth IRA by the return due date including extensions, before any conversion happens. The moment that money converts, though, the decision locks in. Anyone weighing a full Roth conversion of a larger balance faces the same irreversibility, since it applies to any post-2017 conversion, not only the backdoor version.
The Mega Backdoor Roth: A Separate, Larger Strategy
The mega backdoor Roth is a distinct and larger-scale maneuver: some 401(k) plans let participants make after-tax contributions on top of the regular deferral limit, then convert those after-tax dollars to Roth, up to the combined $72,000 IRC section 415(c) limit for 2026, but only if the plan document specifically allows it.
After-tax 401(k) contributions are a separate category from both pre-tax elective deferrals and designated Roth contributions. The overall annual-additions ceiling under IRC section 415(c) combines employee elective deferrals, capped at $24,500 for 2026, employer contributions, and after-tax contributions into one $72,000 total for 2026, with an additional $8,000 catch-up for those 50 and older, or $11,250 for those aged 60 to 63, allowed on top of that limit. Once after-tax dollars are in the plan, they can move to Roth in one of two ways, depending on what the plan allows: an in-plan Roth conversion, or an in-service distribution rolled out to an external Roth IRA. When rolling out to an IRA, IRS guidance permits splitting the distribution so pre-tax amounts go to a Traditional IRA and after-tax amounts go to a Roth IRA in the same transaction.
Availability is the entire caveat. The strategy requires the employer’s plan document to permit after-tax contributions and either in-plan conversions or in-service distributions, features many plans simply do not offer. A Solo 401(k), because it is still a 401(k), can in principle offer the same after-tax and Roth-conversion features if the plan document provides for them, giving some self-employed savers a path to the mega backdoor that a standard SEP IRA does not offer.
Frequently Asked Questions about the Backdoor Roth IRA
Is a backdoor Roth IRA legal?
Yes. It combines two IRS-sanctioned steps, a nondeductible Traditional IRA contribution and a Roth conversion, both permitted under IRC section 408A regardless of income. There is no separate “backdoor Roth” statute because none is needed. The strategy simply uses the conversion rule, which carries no income limit, instead of the direct-contribution rule, which does.
How much can I put into a backdoor Roth IRA in 2026?
The nondeductible Traditional IRA contribution that starts the process is capped at the standard 2026 IRA limit, $7,500, or $8,600 if you are 50 or older. That is the same limit that applies to any IRA contribution, not a special higher backdoor allowance.
What is the pro-rata rule and why does it matter here?
The pro-rata rule under IRC section 408(d)(2) aggregates all your Traditional, SEP, and SIMPLE IRAs into one pool when calculating how much of a conversion is taxable. If you hold pre-tax money in any of those accounts, part of your backdoor Roth conversion will be taxable even though the new contribution itself was nondeductible.
Do I have to file Form 8606?
Yes. Form 8606 documents the nondeductible contribution and, in the conversion year, calculates the taxable portion of the conversion using the combined year-end value of your Traditional, SEP, and SIMPLE IRAs. Without it, the IRS has no record of your basis.
Can I reverse a backdoor Roth conversion if I change my mind?
No. Conversions made on or after January 1, 2018 cannot be recharacterized, a change made by the Tax Cuts and Jobs Act. A regular contribution can still be recharacterized before it is converted, but the conversion itself is permanent.
What is the difference between a backdoor Roth and a mega backdoor Roth?
A backdoor Roth uses a Traditional IRA and is capped at the standard IRA contribution limit. A mega backdoor Roth uses after-tax contributions inside an employer 401(k) plan and can reach the much larger $72,000 IRC section 415(c) limit for 2026, but only when the specific plan document allows after-tax contributions and Roth conversions.
A Note on Getting This Right
This article is educational information about federal retirement account rules, not individualized tax, legal, or financial advice. A backdoor Roth conversion is one piece of a broader tax strategy for retirement savings, not a stand-alone fix, and its value depends heavily on your other IRA balances and your expected tax bracket in retirement. Always consult your own legal, financial, and tax professionals before opening or changing a retirement account.
By Tim Schmidt + Sean Webster Reviewed by Sean Webster